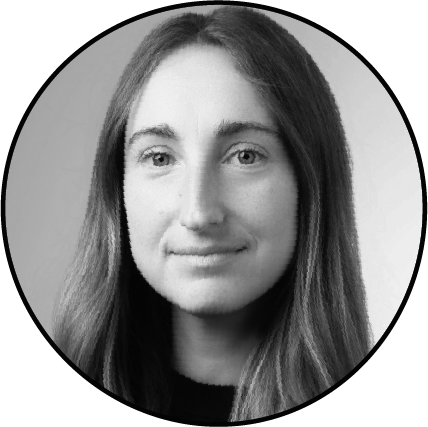
Exclusive interview with Marina Pasika, General Manager - Private Markets, Rest
GLOBAL INVESTMENT INSIGHTS
“We want to understand where value is accruing as economies and industries evolve, and then find the best way to access it. The answer might be private equity, infrastructure, property or alternatives. That means starting with the investment thesis rather than the asset class, and being open-minded about where the most compelling opportunity sits.”
Marina Pasika, General Manager - Private Markets, Rest
Marina is the General Manager of Private Markets at Rest, where she is responsible for the strategy, construction and management of the Fund's private markets portfolio. Marina oversees investments across real assets, private equity and other alternative asset classes, with a focus on generating long-term value for Rest's predominantly young membership base.
Rest is one of Australia's largest profit-to-member superannuation funds with ~A$105 billion in assets under management and more than 2 million members.
In this exclusive interview with Global Investment Institute, Marina discusses Rest’s current priorities for its private markets’ portfolio, where she sees the most compelling relative-value investment opportunities and the key themes Rest is seeking to capture through its private markets investments. She also explores the evolving role of private equity in the broader portfolio, the geographic drivers shaping allocations and the qualities she looks for in external investment managers to build successful, long-term partnerships.
Q. Since your appointment as Rest Super’s permanent General Manager, Private Markets earlier this year, what are the top of the agenda items for you and the key areas you are focused on currently?
A. My focus has been on bringing the full breadth of Rest’s private markets portfolio together and becoming even more intentional about where and how we invest.
We are increasingly looking across traditional asset-class boundaries and focusing on the systems and structural changes we believe will shape economies and investment opportunities over the long term.
That means developing differentiated investment theses around areas of structural change, understanding where value is likely to accrue across those systems and using those insights to originate opportunities more deliberately.
A big part of that is also how we work as a team. We want to bring together perspectives from private equity, infrastructure, property and other private markets so that we can assess opportunities on their merits and through a whole-of-portfolio lens.
Ultimately, the objective is simple: sharper insights, more intentional origination and disciplined execution in the areas where our conviction is strongest.
Q. Where are you currently seeing the most compelling opportunities to put capital to work across private markets, on a relative value basis?
A. I’m cautious about naming a particular asset class as “the” opportunity because that is not how we think about relative value.
We have long focused on the major structural forces shaping the world our members will retire into. Increasingly, we are translating them into specific investment theses across private markets. The energy transition and rising power demand, the continued expansion of the digital economy, changing patterns in how people live, and the evolving industrial systems and supply chains are all creating significant capital needs.
The key question is where within those systems the best risk-adjusted opportunities sit. The answer may be infrastructure, private equity, property or another form of private capital. We seek to understand the underlying value chain, identify where value is accruing and then determine the most attractive way to gain exposure.
That sets a higher bar for capital allocation, because opportunities compete not only within their asset class, but across the entire private markets portfolio.
Q. As more companies stay private and others remain private for longer before listing, are private equity allocations playing a greater role in Rest’s overall portfolio and what are some of the key themes you are looking to gain exposure to?
A. As companies stay private for longer, private markets are becoming a more important part of the opportunity set for long-term investors. Exceptional businesses can now build significant scale and create substantial value before reaching public markets, so the ability to invest through their growth journey matters.
For us, however, the question is less about increasing private equity exposure, and more about accessing the businesses and sources of value creation we find most compelling. We want to be selective and invest where we have real conviction, whether through our managers or more targeted opportunities.
Our investment theses increasingly direct that search. We are particularly interested in businesses positioned to benefit from structural shifts such as AI and digitalisation, the energy transition and reindustrialisation. Private equity offers one route to access those changes, especially where skilled managers can help businesses grow and create lasting value over the long term.
Q. From a regional perspective, which geographies are playing a growing role in your PE portfolio? What are the drivers reshaping your geographic portfolio composition?
A. Our private equity portfolio has a strong US orientation, particularly in the small and mid-markets. This is where we have found the deepest pool of managers with the capabilities we are looking for.
For us, private equity is fundamentally about manager skill and genuine operational value creation. We look for a clear and repeatable playbook for how a manager creates value in its portfolio companies, and evidence that it has applied that successfully deal after deal, fund after fund. That remains the bar wherever we invest. We find the depth of that capability particularly strong in the US.
Our thematic work is also shaping where we look. We are developing investment theses across private markets and then looking for the most attractive way to express them. Some of our work around AI, the digital economy, and reindustrialisation within our industrial system, naturally point us towards the US. We then seek managers that combine exposure to those structural changes with the operational capability to translate them into returns.
We remain open elsewhere, including to Australia’s venture ecosystem where managers offer differentiated capabilities and strong alignment. However, the bar remains the same. Geography is not the diversification objective; a genuine edge is. Managers must create value, rather than rely mainly on market growth, leverage or multiple expansion.
Q. What are the main characteristics you look for in a partnership with an external manager and what defines a successful partnership?
A. The best partnerships go well beyond access to a fund or an individual transaction.
We look for managers with differentiated insight, strong judgement, deep capabilities and local networks in the markets in which they operate. Alignment matters enormously, and so does openness. We value partners who share their thinking, challenge ours and engage with us early rather than simply presenting a finished transaction.
As we become more thesis-led in our approach to private markets, those relationships matter even more. When a manager understands where we have conviction, we can identify and shape investments together rather than wait for something to appear in a conventional pipeline.
The strongest relationships create value well beyond the investment itself; through expertise and insights, co-investment opportunities, innovative structures and better economics over time, as well as building our team capability. The best long-term partnerships combine our perspective as a long-term investor with the manager’s specialist expertise, networks and ability to execute on the ground. They are built on trust, alignment and a willingness to share ideas and explore opportunities together.
Marina Pasika, General Manager - Private Markets, Rest
Marina is the General Manager of Private Markets at Rest, where she is responsible for the strategy, construction and management of the fund's private markets portfolio. She oversees investments across real assets, private equity and other alternative asset classes, with a focus on generating long-term value for Rest's predominantly young membership base.
She is a passionate advocate for systems-led investing, innovation in portfolio construction and building high-performing investment teams. She is particularly interested in how global structural shifts—including decarbonisation, digitalisation, demographic change and the reshaping of supply chains—create long-term investment opportunities across both traditional and emerging sectors, and translating these opportunities into differentiated portfolio outcomes for members.
Marina joined Rest in 2020. Prior to her current role, Marina built and led Rest's Private Equity and Growth Alternatives teams and portfolios and has played a key role in evolving the organisation's approach to portfolio construction and investment decision-making.
Prior to joining Rest, Marina worked in the private equity team at the Future Fund for 9 years, where she invested in private equity funds and co-investments.
Marina previously worked in the Investment Banking Division of Goldman Sachs, where she advised Australian corporations on mergers and acquisitions and financing transactions.
She has a Bachelor of Commerce and Bachelor of Laws (Honours) degree from the University of Melbourne.
Global Investment Institute is Australia’s leading provider of conferences for capital allocators.
We connect institutional investors, family office and private wealth investment leaders with peers and global investment experts to share knowledge and thought leadership in a private, collegiate and discussion-focussed setting, conducted under Chatham House Rule. Attendance is by invitation-only.
We host private gatherings for investment leaders across three distinct segments:
Institutional
Family Offices
Private Wealth (institutional-scale)
Each segment has its own series of dedicated events for delegates to connect with peers and we have an unrivalled network of capital allocators who we invite to attend.
UPCOMING EVENTS